
How to calculate staking returns hinges on distinguishing the platform’s quoted annualized rate from the actual yield after fees, slippage, and compounding method. On-chain data show that staking yields on proof-of-stake networks are generally trending lower; simply multiplying the quoted rate by principal tends to overestimate real returns.
Data show that a major proof-of-stake network hit a record high of roughly 43.8 million staked tokens at the end of Q3, representing about 35.9% of total supply, yet its annualized total staking yield fell from 2.81% in the previous quarter to 2.63%. Another high-performance network’s total staking yield declined from approximately 6.38% to around 6%. The larger the staking base and the higher the quoted rate, the wider the gap between book figures and actual proceeds.
Staking Return Formula and Three Inputs
Staking returns are typically estimated as “principal × annualized yield × staking years,” then compounded according to protocol rules. In practice, convert held tokens into USD value as principal, plug in the yield provided by the validator, custodial platform, or liquid staking protocol, select the staking duration, and obtain a USD-denominated breakdown of projected returns, total interest, and future value. A more conservative approach is to run the calculation twice: once using the platform’s recently paid lowest rate, and once using the highest rate, to produce an interval rather than a single figure.
APR vs. APY: Why the Quoted Rate Cannot Be Used Directly
Both APR and APY express annualized returns, but they differ in whether compounding is included. APR is simple annualization, while APY assumes rewards are reinvested on a periodic basis, so the same principal looks higher under APY. Platforms do not consistently cite one or the other;
comparing different assets without first aligning the metric can easily mislead. The same applies to yield-farming strategy quotes: the higher the total value locked in yield farming, the more intense the competition and the faster per-unit returns are diluted.
Why Yields Keep Declining: Rewards Are Spread Over More Capital
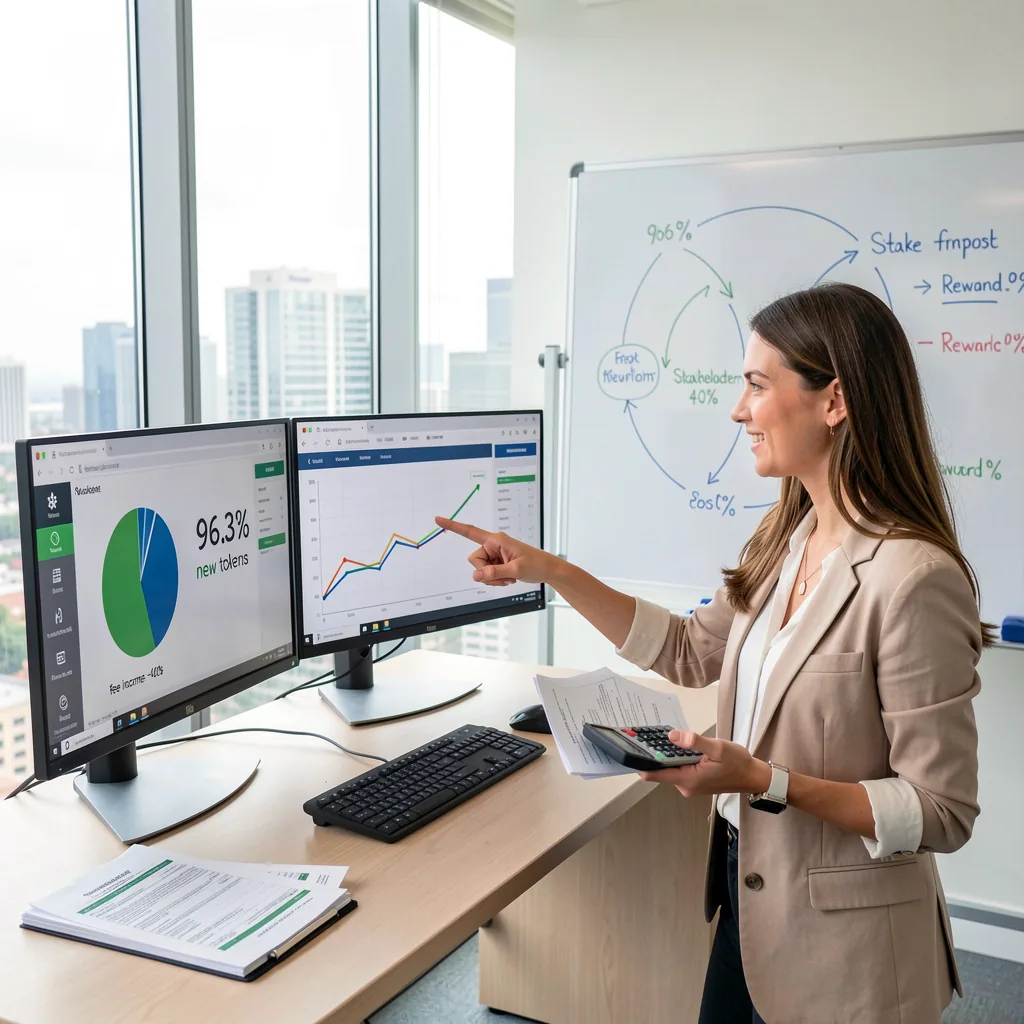
Staking returns mainly come from two sources: newly issued tokens by the protocol, and transaction fees plus priority fees paid by users for ordering. In the aforementioned major network, new issuance contributed about 96.3% of total returns, with the remainder from fees. As net staking inflows remain positive for consecutive quarters and the staking base expands, the same reward pool must be distributed among more funds, naturally compressing yields. The network’s Q3 transaction volume grew over 30% year-on-year, yet average daily network fees and ordering revenue fell roughly 40% quarter-on-quarter;
scaling lowered user costs but has not yet translated into stronger fee generation.
Another network saw activity and fees increase, but lower issuance combined with a larger staking base offset the improvement in rewards; nearly 90% of total staking returns still stem from issuance. Industry observers widely expect that as the staking ratio continues to rise, yields will gradually find balance under the protocol’s reward structure.
From Quoted Rate to Actual Proceeds: Costs and Risks That Must Be Deducted
The quoted rate is only the starting point;
several hurdles stand between it and actual proceeds. Custodial staking and liquid staking providers typically retain a small portion of rewards to cover operational and infrastructure costs. Rewards are denominated in tokens, so if the token price falls, USD-denominated returns are offset. New issuance, when not canceled by burns, dilutes holders’ proportional ownership. Additionally, unstaking and withdrawal involve waiting periods;
liquidity gaps may prevent timely conversion of gains into cash.
On the regulatory front, relevant authorities recently issued a joint interpretive announcement confirming that protocol staking does not constitute a securities transaction, opening compliance space for custodial and liquid staking. Staking-linked exchange-traded funds are also seeing rising demand. For ordinary holders, a more realistic expectation is: first confirm whether the quote is APR or APY, then calculate using both the lowest and highest rates, and finally deduct service fees and potential price volatility;
the resulting interval is far closer to true yield.
Related Reading
How Serious Is the Problem of Decentralized Crypto Exchanges in India? A Set of Data Tells the Answer
Bitcoin has moved sharply lately, so the upside and the risk need to be measured together.
Checking network fees and platform rules before a transfer is especially important for beginners.
The article explains wallet security, exchange selection, and risk control in a practical way.
After experiencing exchange risk controls, I now use 2FA and avoid keeping all funds in one place.